
Advertisement
Did you know that people often treat a surprise $100 birthday gift differently than the same amount earned through work? This fascinating behavior illustrates the concept of mental accounting, a term popularized by Richard Thaler, a pioneer in behavioral economics. It explains why we categorize money based on its source and intended use, leading to varied spending habits.
Mental accounting is the tendency to assign different values to money, which can simplify our everyday financial choices. However, it can also lead to impulsive spending and inconsistent financial decisions. For instance, someone might spend a tax refund freely while being hesitant to touch their savings.
This article will explore how our perceptions of money can influence our financial decisions. We’ll discuss concepts like windfalls, mental budgets, and the emotional aspects of spending. By recognizing these patterns, you can make choices that better align with your long-term financial goals.
Understanding Mental Accounting: A Beginner’s Guide
Have you ever noticed how a cash gift can feel more like ‘fun money’ than your regular paycheck? This is a perfect example of mental accounting, a concept introduced by the renowned economist Richard Thaler. It describes how we categorize our finances into different mental buckets based on their source or intended use.
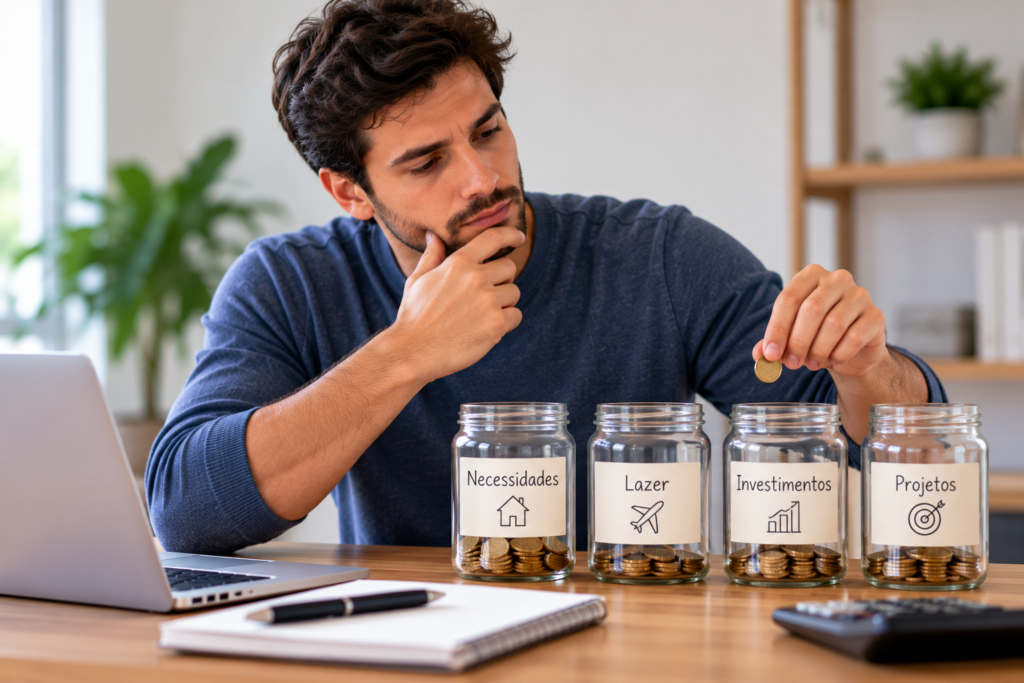
At its core, mental accounting is the process of placing money into psychological categories. These categories might include savings, bills, entertainment, or gifts. Although each dollar holds the same value economically, people often treat money differently based on its label. For instance, $20 earned from a job may feel more significant than $20 received as a gift.
This tendency can lead to irrational financial decisions. People might hesitate to use their ‘savings’ to pay off high-interest debt, even if it makes financial sense. The labels we assign to money can influence our spending and saving habits in ways that don’t always align with our best interests.
Understanding this concept can empower you to make more informed financial choices. By recognizing how you categorize your funds, you can work towards aligning your spending with your long-term goals.
| Type of Money | Example | Typical Behavior |
|---|---|---|
| Earned Income | Salary | Careful budgeting |
| Gift Money | Birthday Cash | Spending freely |
| Emergency Funds | Rainy Day Savings | Reluctant to use |
| Windfall Gains | Tax Refund | Impulsive spending |
In summary, mental accounting plays a significant role in how we perceive and manage our finances. By understanding these mental categories, you can begin to make choices that better reflect your financial priorities.
The User Intent Behind Mental Accounting
Many consumers treat unexpected gains differently than their regular income, shaping their financial choices. This tendency is a core principle of mental accounting, where individuals create mental categories for their money. These categories can significantly influence how they evaluate income, savings, and purchases.
People rarely assess money in absolute terms. Instead, they compare it with expectations, labels, and specific goals surrounding a transaction. For example, someone might guard their vacation fund while still carrying credit card debt. This happens because they have assigned that money to a separate mental account, viewing it as untouchable.
These mental categories help create a sense of control and predictability in an otherwise complex financial life. Individuals often find comfort in labeling their funds, whether it’s for a bonus, a tax refund, or a gift card. However, this can lead to irrational decisions. For instance, they might avoid using savings to pay off debt, even if it’s the most financially sound choice.
Concrete thinking tends to produce narrower accounts, making financial labels feel more rigid. On the other hand, broader thinking can encourage individuals to view all their money as part of one financial system. Recognizing these patterns doesn’t mean eliminating every budget category; it means understanding when a category helps or limits better decisions.
Money Is Fungible — Or Is It? Exploring the Myth
Isn’t it interesting how we perceive money based on its source? The concept of fungibility plays a crucial role in understanding our financial decisions. Fungibility means that money is interchangeable; one dollar has the same value regardless of its origin—be it wages, gifts, or refunds. However, the way we experience money often contradicts this principle.
In the realm of economics, the economy treats all dollars equally. Yet, many people create distinct mental categories for their funds. For example, someone might keep money in a low-interest savings account while carrying high-interest credit card debt. This separation occurs because they perceive these funds differently, even though combining them could enhance their overall financial health.
The Economic Principle of Fungibility
Fungibility suggests that every dollar can be exchanged freely. In theory, it doesn’t matter whether money comes from a paycheck or a bonus; its purchasing power remains unchanged. However, this view doesn’t align with how individuals manage their finances. People often attach emotional significance to money based on its source, which can lead to poor financial choices.
How Mental Accounting Challenges Fungibility
Consider this: when you receive a tax refund, you might feel inclined to spend it on a luxury item. Yet, the same amount of money, if earned through work, might be saved for future expenses. This behavior illustrates how mental accounting challenges the idea of fungibility. The source of a dollar can change its emotional meaning, even though its economic value remains constant.
- Money can be exchanged freely, but people often assign labels like “gift money” or “vacation money.”
- The economy does not recognize these labels, but they significantly impact spending decisions.
- Maintaining savings while carrying debt can lead to unnecessary financial strain.
- Understanding the emotional weight of money can help address larger financial priorities.
- Ask yourself: Would you make the same financial decisions if all your money were viewed in one complete picture?
Recognizing these patterns can empower you to make better financial decisions. By understanding how you categorize your funds, you can work towards a more cohesive financial strategy that aligns with your goals.
| Source of Money | Perceived Value | Typical Financial Behavior |
|---|---|---|
| Wages | Stable and essential | Careful budgeting |
| Gifts | Fun and discretionary | Impulsive spending |
| Refunds | Unexpected windfall | Luxury purchases |
| Savings | Reserved for emergencies | Reluctant to use |
Mental Accounting in Action: How We Label and Categorize Money
People often view additional funds through a unique lens, distinguishing between regular earnings and unexpected windfalls. This behavior is a fundamental aspect of mental accounting. It shows how individuals categorize money based on its source and intended use.
Regular Income vs. Windfall Gains
When it comes to spending, regular income and windfall gains are treated quite differently. Regular income, such as a paycheck, is often seen as essential for day-to-day living. In contrast, windfall gains—like bonuses or tax refunds—are frequently viewed as extra money, making them feel easier to spend.
For example, a tax refund represents money that was overpaid, yet many treat it as a bonus. This perception can lead to impulsive spending on luxury items rather than investing it wisely.
The Role of Mental “Bank Accounts”
Individuals create mental “bank accounts” for various categories, such as rent, food, savings, and entertainment. These categories can help with budgeting, but they may also encourage people to spend one pool of funds freely while ignoring urgent financial needs elsewhere.
For instance, someone might feel comfortable spending from their entertainment fund, while hesitating to use savings for debt repayment, even if that would be the more financially sound choice.
Gift Cards and Brand-Specific Spending
Gift cards illustrate how labeling can influence spending behavior. A gift card for a specific retailer, like Levi’s, often leads consumers to purchase items that align with that brand. This can result in a narrower focus on what to buy, even though the dollar value remains the same.
When faced with a Levi’s gift card, individuals are more likely to buy jeans associated with the brand rather than a less specific item, like a sweater. This demonstrates how the mental label of the card shapes their spending decisions.
Understanding these patterns helps clarify why we spend money differently based on the source of our funds. By recognizing how we categorize money, we can make smarter financial choices that align with our long-term goals.
How Situations Shape Our Idea of Value and Spending
Have you ever considered how the setting can change your perception of a product’s value? This idea is known as transactional utility. It refers to the satisfaction people feel when they believe they received a good or reasonable deal. Understanding this concept can help you make smarter financial choices.
Consumers often accept high prices for items in specific contexts. For example, think about the prices for popcorn at a movie theater or food at a stadium. Many are willing to pay more in these situations, even if the same items are available for less elsewhere. Why does this happen?
Transactional Utility and Its Effects
Consider a classic experiment involving beer pricing. Participants were willing to pay a median of $2.65 for a beer at a fancy resort hotel. In contrast, they only valued the same beer at $1.50 when it came from a small, run-down grocery store. Both groups enjoyed the beer on the same beach, illustrating that context significantly shapes perceived value.
Paying Premium Prices by Context
Atmosphere, expectations, and social context can make a premium feel more acceptable. When enjoying a day at an amusement park, you might not think twice about spending more on a drink than you would at home. This is because the environment creates a different perception of value.
It’s essential to recognize when a “special occasion” influences your spending. Are you overlooking a high cost simply because the setting feels festive? Understanding these influences can help you identify when you’re redefining what counts as a good deal.
Framing Effects: Gains, Losses, and How We Perceive Them
Have you noticed how presenting the same amount of money differently can alter your decision-making? This phenomenon is known as framing, and it plays a significant role in how we interpret financial outcomes. The way information is presented can greatly influence our choices and perceptions of value.
The Calculator Study and Topical Framing
A fascinating study by Daniel Kahneman and Amos Tversky highlights this effect. In their research, 68% of participants were willing to drive 20 minutes to save $5 on a $15 calculator. However, only 29% would make the same drive to save $5 on a $125 calculator. The savings were identical, yet the context made a huge difference. The smaller purchase made the savings feel more significant.
This is an example of topical framing, where people judge a gain based on the specific item or category being discussed. When savings are framed in relation to a smaller expense, they seem more valuable.
Integrated vs. Segregated Gains and Losses
Research shows that people generally prefer segregated gains. For instance, receiving two separate rewards of $50 and $25 can feel better than one combined reward of $75. This tendency highlights how we perceive gains differently based on their presentation.
In contrast, losses often feel less painful when integrated into one larger event. For example, experiencing a single $150 tax bill is less distressing than receiving two separate bills of $100 and $50. This illustrates how framing can influence our emotional response to financial situations.
Consider car purchases: optional extras may seem minor because they are added to a much larger financial loss. When presented as part of a total cost, they may feel less significant, leading to different spending choices.
Ultimately, it’s essential to compare total dollar outcomes rather than relying solely on how a deal or fee is presented. Understanding these framing effects can empower you to make better financial decisions that align with your long-term goals.
The Pain of Paying: Why Spending Feels Different Depending on Method
Have you ever thought about how different payment methods can affect your feelings about spending? The pain of paying describes the emotional discomfort that comes with spending money. This discomfort can make even planned purchases feel like a small financial loss.
When you use cash, the experience is immediate. Handing over bills makes you acutely aware of the cost. Your wallet visibly thins, creating a tangible sense of loss. In contrast, using a credit card can lessen this discomfort. With credit, the account balance doesn’t change right away, making spending feel less impactful.
Digital wallets and tap-to-pay methods also abstract the experience. These payment methods can make spending feel like a breeze, especially when the payment occurs after enjoying the product or service. This separation can lead to overspending, as the immediate cost isn’t felt.
Delayed payments, such as those in subscription models, further distance consumption from payment. When you subscribe to a service, the smaller recurring payments may hide the total annual cost. This can make the purchase feel less significant, encouraging more frequent spending.
Consider the following points:
- The pain of paying can create discomfort, even with planned purchases.
- Cash payments provide immediate awareness of costs, while credit cards can make spending feel abstract.
- Digital payments often lead to a lack of awareness about spending, especially when payment is delayed.
- Subscription models can obscure the total cost, leading to potential overspending.
- Regularly reviewing recurring charges can help you understand your financial commitments better.
By understanding these effects, you can make more informed choices about how you spend. Remember to pause before treating frictionless payments as free. This awareness can lead to smarter financial decisions.
| Payment Method | Emotional Impact | Typical Spending Behavior |
|---|---|---|
| Cash | Immediate awareness of cost | Careful spending |
| Credit Card | Abstract feeling of spending | More impulsive purchases |
| Digital Wallet | Less emotional connection | Frequent spending |
| Subscription | Hidden total cost | Overlooked recurring charges |
How Mental Accounting Influences Everyday Financial Choices
Have you ever realized how the way we categorize money can shape our daily financial choices? This concept plays a significant role in how individuals manage their savings and debt. Often, people maintain savings accounts earning little interest while carrying high-interest credit card debt. This occurs because savings and debt are treated as separate accounts in our minds.
When considering payments, it’s essential to recognize that paying down high-interest credit card debt can be a stronger financial decision than preserving low-yield savings. However, it’s also crucial to maintain an appropriate emergency reserve. The emotional impact of debt payments can feel like a loss, while savings balances often seem like achievements, even when the overall financial result is unfavorable.
Managing Savings vs. Paying Off Debt
Individuals frequently face the dilemma of whether to pay off debt or save. For example, a person might choose to keep funds in a savings account rather than use them to pay off a credit card balance. This decision can stem from the mental accounting process, where debt payments are viewed negatively, and savings are seen positively.
Windfall Spending and Tax Refunds
Tax refunds and windfall money are often perceived as bonus funds. This perception can lead to more carefree spending compared to regular income. For instance, a tax refund might be spent on entertainment or travel instead of being allocated toward debt reduction. Understanding this tendency can help individuals make better financial decisions.
To make the most of unexpected money, consider a practical framework. Divide windfall funds among urgent debt, savings, planned expenses, and a small amount for enjoyment. This approach ensures that you address financial priorities while still allowing for some fun.
Choice Bracketing and Mental Budgets
Choice bracketing refers to how broadly or narrowly people evaluate financial decisions. A small daily expense, like a $5 coffee, may seem minor when viewed in isolation. However, when considered over a year, that daily coffee adds up to $1,825. This example highlights the importance of recognizing cumulative expenses when reviewing a budget.
Encouraging readers to combine related choices when budgeting can help illuminate their overall spending habits. Isolated purchases may hide their cumulative effect, leading to less informed financial decisions.
| Financial Decision | Common Behavior | Impact on Budget |
|---|---|---|
| Paying Off Debt | Often viewed as a loss | Can lead to financial strain |
| Maintaining Savings | Seen as an achievement | May neglect urgent debt |
| Spending Tax Refunds | Spent freely | Less likely to reduce debt |
| Daily Small Expenses | Minimized in isolation | Significant annual totals |
Conclusion: Using Mental Accounting to Make Smarter Money Decisions
Have you ever realized that the way we categorize our finances can shape our decisions? Mental accounting explains why we often treat dollars differently, even though they are economically fungible. By being aware of this tendency, you can improve your financial decisions significantly.
Consider asking yourself: Am I treating this money differently because of where it came from? Would I make the same choice if all my funds were interchangeable? The goal is not to eliminate budgeting categories but to use them to support your long-term financial well-being.
Reflect on how you handle windfalls, tax refunds, and credit balances. Review these as parts of one complete financial picture. Understanding these patterns gives you more control over your spending and saving habits.
In conclusion, recognizing how you categorize money can lead to smarter financial choices that align with your goals. Embrace this awareness to make decisions that truly reflect your priorities.