
Advertisement
Did you know that nearly 60% of Americans report feeling financially stuck, even after receiving a raise or promotion? This phenomenon, known as lifestyle creep, occurs when increased income leads to higher spending rather than greater savings. While earning more can enhance your quality of life, it can also slow down your wealth-building efforts.
Many people find themselves enjoying the perks of their hard work, yet they still struggle to meet financial goals. This imbalance can delay significant milestones, such as buying a home or retiring comfortably. The challenge lies in striking a balance between enjoying life today and securing your financial future.
In this article, we will explore practical advice on budgeting, saving, and investing. We’ll help you recognize the signs of lifestyle inflation and create a plan to align your spending with your long-term goals. Together, we can work towards a future where your finances support your dreams, not hinder them.
Understanding Lifestyle Creep: What It Is and Why It Happens
When income rises, many find themselves unknowingly increasing their expenses. This phenomenon, known as lifestyle creep, refers to the gradual expansion of regular spending as a person’s income increases. Often, this increase in spending occurs without a corresponding rise in savings.
Common examples of lifestyle creep include moving into more expensive housing, dining out more frequently, and choosing premium brands. Upgrading phones and computers, purchasing pricier furniture, and adding new subscriptions can also contribute to this trend. Even vacations can become more extravagant as people feel justified in their spending due to their higher earnings.
These changes can happen subtly, often without conscious decision-making. Major life events such as receiving a raise, a bonus, a promotion, or even starting a new job can trigger these spending increases. Family changes, like marriage or having children, can also make higher spending feel necessary.
It’s essential to distinguish between purposeful lifestyle improvements that align with personal values and lifestyle inflation that quietly consumes money needed for future priorities. While enjoying life is important, maintaining a balance is crucial for long-term financial health.
To assess whether a new expense is a one-time treat or a permanent change, consider its impact on your overall budget. Is it a recurring commitment that will affect your savings and financial goals? Taking the time to evaluate these expenses can help you maintain control over your financial situation.
Signs You’re Experiencing Lifestyle Creep
Many people overlook the subtle signs that their spending habits are changing as their income grows. Understanding these signs can help you regain control over your finances and ensure your increased earnings contribute to your wealth-building journey.
Decreasing Savings Despite Increasing Income
One of the most telling signs of lifestyle creep is a noticeable decrease in your savings rate. If you find yourself saving less even though your income has risen, it’s time to reassess your financial habits. Compare your current savings rate with what it was before your income increase. This comparison can reveal whether your financial position has genuinely improved.
Rising Expenses and Growing Debt
Another indicator of lifestyle inflation is the rise in your monthly expenses. If you notice that your grocery bills, housing costs, and entertainment expenses have increased, you may be experiencing lifestyle creep. Many people find themselves relying more on credit cards to manage these higher costs. Keep an eye on your credit card balances and minimum payments; they can signal that your spending exceeds what your income can sustainably support.
Feeling “Paycheck to Paycheck” Even with Higher Earnings
Feeling like you’re living paycheck to paycheck, despite earning more, is a common emotional sign of lifestyle creep. This situation can leave you feeling trapped, unable to return to previous spending habits. Review your bank and credit card statements to identify purchases that have become routine but may no longer align with your financial goals. It’s crucial to recognize these patterns before they hinder your financial future.
How Lifestyle Creep Impacts Your Wealth Building Journey
As your income increases, it can be easy to let your spending habits spiral out of control. This phenomenon can significantly affect your ability to build wealth over time. Understanding the short-term and long-term effects of this behavior is crucial for your financial health.
In the short term, increased discretionary spending can crowd out emergency savings. This situation leaves households less prepared for unexpected costs, such as medical bills or car repairs. Many people find themselves relying more on credit cards to manage these higher expenses. As a result, they become vulnerable to job changes or sudden financial emergencies.
Short-Term Effects on Emergency Savings and Debt
- Higher spending can prevent the establishment of a robust emergency fund, which is essential for financial security.
- Relying on credit cards for everyday expenses can lead to high-interest debt, diverting future income toward interest payments instead of savings.
Over time, these short-term effects can compound into significant long-term consequences. Higher spending reduces contributions to retirement accounts, delaying the growth of your investments. This delay limits the benefits of compound growth, making it harder to achieve financial independence.
Long-Term Consequences for Retirement and Financial Freedom
- Lower retirement contributions today can lead to smaller investment balances tomorrow, which affects your ability to retire comfortably.
- Lifestyle creep can postpone critical goals such as homeownership, education funding, and career flexibility.
It’s important to note that the impact of lifestyle creep is not solely determined by income level. The relationship between income, spending, savings, and personal priorities plays a significant role in your financial journey.
To illustrate the importance of maintaining a balanced approach, consider the following guidelines:
| Financial Goal | Recommended Savings |
|---|---|
| Emergency Fund | 3-6 months of essential living expenses |
| Retirement Savings | 10-15% of gross income |
By keeping these guidelines in mind, you can better navigate the challenges of lifestyle creep and ensure your finances align with your long-term goals.
Practical Budgeting Techniques to Combat Lifestyle Creep
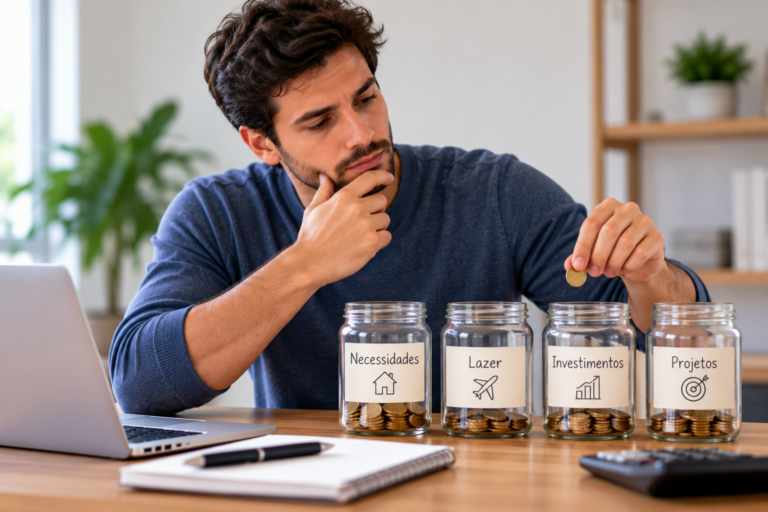
Many individuals find themselves overwhelmed by spending habits that seem to expand alongside their income. Creating a solid budget is essential to track your income and expenses. A well-structured budget helps set limits for nonessential spending and protects your savings goals.
Two popular budgeting models can guide you:
Creating and Sticking to a Realistic Budget
Start by crafting a monthly spending plan based on your actual take-home pay. Include fixed bills, variable expenses, debt payments, savings, investments, and realistic discretionary spending. This approach allows you to see where your money goes and identify areas for improvement.
Popular Budgeting Models: 50/30/20 and 60/30/10+15 Guidelines
The 50/30/20 model is a straightforward starting point. It allocates 50% of your take-home pay to needs, 30% to wants, and 20% to savings and debt repayment. On the other hand, the 60/30/10+15 guideline suggests using no more than 60% of your take-home pay for essentials, 30% for nonessentials, 10% for near-term goals and emergency savings, and 15% of pretax income for retirement. This model allows for more precise separation of your expenses.
Using Digital Tools and Apps to Track Spending
In today’s digital age, using budgeting apps or spreadsheets can simplify your financial management. These tools help you set spending limits, monitor progress, and review your plan monthly or whenever your income or expenses change. Make sure to regularly check your bank statements, credit card activity, and digital subscriptions to identify categories where spending has increased due to lifestyle creep.
Remember, budgeting models are flexible frameworks rather than strict rules. They should accommodate your household size, location, income changes, and debt obligations. By implementing these practical budgeting techniques, you can effectively combat lifestyle creep and work towards your financial goals.
Saving and Investing Strategies to Stay Ahead of Lifestyle Creep
Establishing effective savings and investment strategies is crucial to avoid falling into the trap of increased spending as your income grows. Implementing these strategies can help you build wealth while maintaining control over your finances.
One of the best methods to ensure you save effectively is by automating your savings and investment contributions. By setting up automatic transfers, you can direct a portion of your paycheck, raise, or bonus toward your savings account or retirement plan before you even see it. This proactive approach prevents you from spending that money on nonessential items.
Automating Savings and Investment Contributions
Paying yourself first means prioritizing savings and investments as soon as your income arrives. This strategy ensures that you focus on your financial goals before discretionary spending occurs. Consider increasing your automatic contributions whenever you receive a raise or bonus. Aim to direct at least half of each increase toward savings or debt repayment.
Prioritizing Emergency Funds and Retirement Accounts
Building a solid emergency fund is essential. Start with a goal of $1,000, then work towards saving three to six months of essential expenses. This fund will protect you from unexpected costs and help you avoid relying on credit cards.
Additionally, make sure to contribute enough to your workplace retirement plan to capture the full employer match. Utilizing tax-advantaged accounts such as 401(k)s and IRAs can significantly boost your retirement savings. If eligible, consider adding a Health Savings Account (HSA) to your strategy.
Paying Down High-Interest Debt to Free Up Cash Flow
Another effective strategy is to focus on paying down high-interest debt. Reducing this burden can improve your cash flow, allowing you to allocate more money toward savings and investments. As you eliminate debt, you create more room in your budget for future financial goals, such as homeownership or further investments.
By implementing these saving and investing strategies, you can effectively combat lifestyle creep and ensure that your financial future remains secure. Stay proactive, and your finances will support your dreams instead of hindering them.
Mindful Spending and Financial Goal Setting to Manage Lifestyle Creep
Navigating the complexities of spending can feel overwhelming, especially when your income rises. Practicing mindful spending is a powerful way to ensure your purchases align with your values and financial goals. Before making a purchase, ask yourself: Is this item necessary? Does it truly enhance my life? This self-reflection can help curb impulse buys that lead to financial strain.
Practicing Mindful Spending: Questioning Purchases and Waiting Periods
One effective technique is to implement a waiting period for nonessential purchases. For smaller items, consider waiting 24 hours. For larger purchases, extend this to one or two weeks. This approach allows time to evaluate whether the item genuinely fits your budget and lifestyle.
Additionally, using a price-tag rule can help. Estimate the cost of an item before checking its actual price. This method encourages more thoughtful spending. Creating a written buy list can also distance you from emotional purchases, keeping your finances on track.
Setting SMART Financial Goals to Guide Your Spending
Transforming broad intentions into SMART financial goals is crucial. SMART stands for Specific, Measurable, Achievable, Relevant, and Time-bound. For example, aim to save a specific amount for a home down payment by a certain date. Alternatively, set a goal to pay off a credit card balance within a set period. These defined objectives provide clear direction for your spending.
Tracking Progress and Adjusting Plans as Needed
Regularly tracking your financial progress is essential. Review your budget and goals monthly. Adjust your spending, savings, and investment plans whenever your situation changes, such as after a raise, job change, or family addition. Staying flexible ensures your financial strategies remain aligned with your life goals.
By incorporating mindful spending practices and setting clear financial goals, you can effectively manage lifestyle creep. Remember, it’s about finding a balance that allows you to enjoy life while building a secure financial future.
Conclusion
Many individuals find it challenging to balance their newfound income with their spending habits. Lifestyle creep often develops gradually, leading to small increases in expenses that can significantly impact savings and debt over time.
The solution isn’t about total deprivation; instead, it’s about spending intentionally. Directing enough income toward emergency savings, retirement, and investments is essential.
Make sure to use a budget, automate transfers, and monitor credit card activity. Revisit your financial plan whenever your situation changes, like after a raise or new job.
Remember, every financial goal becomes easier to manage when it is specific and connected to personal reasons, such as buying a home or reducing debt. Review your past month of expenses, identify one creeping cost, and create a realistic plan for the next year.