
Advertisement
Did you know that nearly 70% of Americans admit to making impulse purchases? This surprising statistic highlights the importance of understanding financial friction. In simple terms, financial friction refers to the barriers that slow down financial transactions. These can include costs, delays, and behavioral hurdles that disrupt our spending habits.
While it might seem that these barriers are negative, they can actually serve a purpose. A moment of pause can protect you from buying items you don’t need. For instance, setting a waiting period before making a purchase can help you reconsider your decision.
Moreover, it’s essential to distinguish between natural market barriers, like credit limits, and intentional personal safeguards, such as spending caps. By recognizing how these elements play a role in our daily lives, we can better manage our spending and avoid unnecessary purchases.
Understanding User Intent: Why Financial Friction Matters
Impulse buying is a common behavior that affects nearly 70% of Americans. Understanding the concept of financial friction is essential. It creates resistance between individuals, firms, or institutions and their financial decisions. This resistance can play a crucial role in shaping our spending habits.
Readers may encounter the term in various contexts, such as economics, personal finance, and banking. It is also relevant in discussions about impulse buying. By grasping this concept, you can better understand how it relates to your money management.
This guide caters to two main audiences. First, it addresses those interested in macroeconomics. Second, it provides insights for consumers looking for practical spending controls. Both groups can benefit from understanding how financial friction influences decision-making.
Market design significantly impacts how easily people can borrow, pay, invest, and purchase. The way financial systems are structured can either facilitate or hinder transactions. Thus, it’s vital to consider how these barriers affect your choices.
Our aim is to translate technical research into useful insights. Not every financial barrier is beneficial, and it’s important to recognize when they serve a purpose. By understanding these dynamics, you can make more informed purchasing decisions.
| Concept | Description |
|---|---|
| Financial Friction | Resistance in making financial decisions |
| Market Design | Structure influencing borrowing and spending |
| Macroeconomics | Study of economy-wide phenomena |
| Impulse Buying | Unplanned purchases often driven by emotions |
Defining Financial Friction: Economic and Psychological Perspectives
Many people are unaware of how barriers in the financial system impact their spending habits. Financial friction refers to any factor that prevents funds from moving freely or at a frictionless price. These barriers can manifest in various forms, such as interest rates, collateral requirements, credit scores, and fees.
For instance, high interest rates can create measurable resistance, making it more challenging for individuals to access credit. Similarly, information gaps can hinder understanding of one’s financial options, leading to poor decision-making.
On the psychological side, friction adds time or effort between an emotional urge and a completed purchase. This pause can be beneficial, allowing individuals to reconsider their choices before spending. It’s essential to differentiate between barriers caused by a financial crisis and those created for personal self-control. The former is often involuntary, while the latter is a conscious decision to manage spending.
Institutions like the Federal Reserve focus on system-wide stability, aiming to minimize risks in the financial system. In contrast, individuals can implement smaller controls in their daily lives to help curb impulsive spending.
The Role of Financial Friction in Curbing Impulse Purchases
A significant number of consumers struggle with impulse purchases that disrupt their financial stability. One way to combat this is through the concept of financial friction. This refers to barriers that slow down or complicate the purchasing process, allowing consumers time to think.
Instant checkout options often eliminate decision time, making it easy to buy on a whim. However, introducing a modest barrier, like a waiting period, can restore that time. This pause encourages individuals to reflect on whether a purchase aligns with their financial goals.
Moreover, the availability of credit can create a sense of detachment from spending. When payment is separated from the act of consumption, it can feel less immediate. This separation may lead to overspending, as the cost doesn’t hit home right away.
To effectively manage spending, it’s wise to use friction selectively. For nonessential purchases, implementing barriers can help. Meanwhile, necessary bills and emergency access should remain convenient. The aim here is not to punish or deprive oneself but to create a deliberate pause that enhances the quality of financial decisions.
Ultimately, the evidence suggests that when financing becomes more difficult, costly, or delayed, decisions change. By applying these principles, consumers can better navigate their spending habits and curb impulsive purchases.
Key Types of Financial Frictions in Markets and Macroeconomics
Understanding the different types of barriers in financial markets is crucial for consumers and businesses alike. These barriers can significantly affect borrowing and lending practices. In this section, we will explore three key areas where financial frictions manifest.
Credit Market Frictions and Borrowing Constraints
Credit market frictions create barriers that make borrowing more expensive or less accessible. These can include high collateral requirements and costly state verification processes. Such constraints can limit access to funds for many borrowers, particularly small businesses and individuals.
When borrowers face these challenges, it can lead to reduced spending and investment. This, in turn, affects overall economic growth. For firms, limited access to credit can hinder hiring and production, creating a ripple effect throughout the economy.
Banking Sector Frictions and Systemic Risks
Within the banking sector, frictions can arise from issues like bank runs and rollover risks. These problems can transmit shocks from borrowers to the wider economy. When banks face liquidity issues, they may tighten lending standards, making it harder for firms to secure necessary financing.
Moreover, vulnerabilities in shadow banking can exacerbate these risks. Financial policymakers must monitor these frictions closely to maintain economic stability.
Interest Rate Spreads and Their Economic Impact
Interest rate spreads serve as useful indicators of perceived risk and financing pressure. For example, the difference between borrowing costs for BAA-rated private firms and U.S. government borrowing costs can widen during economic downturns. This widening reflects increased risk perception among lenders.
When interest rates rise, it can signal tighter credit conditions, leading to lower investment and hiring by firms. Understanding these dynamics is essential for policymakers who aim to foster a stable economic environment.
| Type of Friction | Description |
|---|---|
| Credit Market Frictions | Barriers making borrowing expensive or less available |
| Banking Sector Frictions | Issues that can transmit problems from borrowers to the economy |
| Interest Rate Spreads | Indicators of perceived risk and financing pressure |
How Financial Friction Affects Firms and Investment Decisions
Firms often face hurdles that can hinder their growth and investment potential. These barriers can manifest as capital constraints, which limit a company’s ability to purchase equipment or adopt new technologies. Even profitable businesses may delay investment when they cannot access affordable external finance.
When firms encounter capital constraints, they may struggle to expand their capacity. This lack of investment can lead to slower growth and diminished productivity. As noted by Maarten de Ridder, reduced investment in productivity can result in long-term output losses, especially after financial crises.
Another important factor is agency costs. These are the extra expenses that arise when lenders cannot fully observe or control how borrowers use funds. Smaller or younger firms often face greater challenges in accessing credit compared to established companies. This discrepancy can create a significant barrier to growth.
Lower investment not only affects individual firms but also has broader implications for the economy. It can lead to weaker productivity growth, reduced output, and slower economic recovery. In summary, understanding these dynamics is crucial for navigating the complexities of investment decisions in today’s financial landscape.
Financial Friction in the Context of Macroeconomic Shocks and Crises
The impact of economic fluctuations can deeply affect consumer behavior and spending habits. Understanding how these shifts influence financial systems is vital for navigating challenges. In this section, we will explore how normal times differ from crisis times and the implications for business cycles and economic stability.
Normal Times vs. Crisis Times: Different Shock Dynamics
During normal times, shocks often stem from changes in borrower risk and relationships between banks and nonfinancial borrowers. These shocks are typically manageable and can be absorbed without severe consequences. However, crisis times introduce shocks that originate within the financial system itself. Such banking-system failures can lead to much larger economic damage.
Research indicates that these rare events create persistent disruptions. They prevent the economy from quickly returning to its previous path, resulting in long-lasting effects on employment and investment.
Implications for Business Cycles and Economic Stability
Financial barriers can amplify economic shocks. For instance, falling asset values and weaker balance sheets lead to additional lending restrictions. This amplification creates a cycle of reduced spending and investment, further destabilizing the economy.
Banking stress impacts various factors, including employment and household confidence. As these elements deteriorate, the timing of business cycles can shift, leading to prolonged economic downturns.
To effectively manage these challenges, crisis prevention often focuses on resilience. Building a robust financial system before a shock occurs is crucial for mitigating future risks.
| Type of Shock | Description |
|---|---|
| Normal Times Shocks | Changes in borrower risk and bank relationships |
| Crisis Times Shocks | Failures within the financial system causing larger damage |
| Amplification Effects | Falling asset values leading to tighter lending |
| Economic Stability Impacts | Effects on employment, investment, and business cycles |
The Federal Reserve and Financial Frictions: Policies and Interventions
The Federal Reserve plays a crucial role in managing economic challenges through its interventions. One of its primary functions is to address financial barriers that can impact borrowing and spending. By implementing effective policies, the Fed aims to stabilize the economy and reduce pressures on consumers and businesses.
One of the main tools at the Fed’s disposal is monetary policy. When private borrowing costs rise, lowering policy rates can help ease financing pressure. This action makes loans more affordable, encouraging spending and investment. However, it’s important to note that monetary policy may be less effective when banks or borrowers face severe constraints. In such cases, even lower rates might not stimulate borrowing as intended.
Monetary Policy Tools to Manage Financial Frictions
To effectively manage financial barriers, the Federal Reserve employs various monetary policy tools. These tools include adjusting interest rates and controlling the money supply. By doing so, the Fed can influence economic activity and promote stability.
Moreover, the Fed provides lender-of-last-resort facilities to support parts of the financial system. This support is crucial during times of stress, but it may not extend to shadow banking institutions, which can create gaps in financial safety.
Macroprudential Regulation and Crisis Prevention
Macroprudential regulation is another key strategy used to limit risks before they escalate into system-wide crises. This approach focuses on addressing vulnerabilities in the financial system, such as bank runs and excessive leverage. By implementing capital buffers and liquidity standards, the Fed aims to enhance the resilience of financial institutions.
Stress tests and supervision are also vital components of this regulatory framework. They ensure that banks can withstand economic shocks and continue to operate effectively. Distinguishing between public policy designed for financial stability and personal spending rules is essential. While the former focuses on the broader economy, the latter helps individuals manage discretionary purchases.
Evidence and Research Findings on Financial Frictions
Exploring the role of financial barriers can reveal important insights into consumer and business decisions. Researchers have studied how these barriers impact economic performance. This includes looking at interest spreads, lending volumes, and investment patterns.
For example, interest rate spreads between different types of debt can indicate how accessible credit is for businesses. These spreads can reflect the perceived risk in the market. When spreads widen, it often signals that borrowing costs are increasing, which can slow down economic activity.
However, it’s important to note that a single statistic cannot capture every form of financial constraint. The relationship between credit conditions and economic output is complex. Researchers often distinguish between correlation and causation in their analyses.
Using U.S. data, we can see trends that are relevant to households and policymakers. For instance, during a crisis, credit becomes tighter, which can lead to reduced spending and slower recovery. This highlights the importance of understanding how financing conditions affect the economy.
Evidence generally supports the idea that financing conditions matter. Yet, there is still room for debate about the size of individual effects. Different studies may show varying results, but the consensus remains that financial barriers play a crucial role in shaping economic outcomes.
| Research Focus | Description |
|---|---|
| Interest Spreads | Indicators of credit accessibility and market risk |
| Lending Volumes | Amount of credit available to businesses and consumers |
| Investment Patterns | Trends in how firms allocate resources |
| Economic Output | Overall productivity and growth influenced by credit conditions |
Financial Friction as a Tool to Prevent Impulse Purchases
Have you ever considered how a brief pause before spending can influence your financial choices? This concept mirrors the broader economic idea that when money isn’t instantly available, buyers tend to reassess their decisions. By implementing small delays, you can create barriers that help you think twice before making nonessential purchases.
Introducing thoughtful pauses can be a game-changer. For instance, you might adopt a 24-hour or 48-hour waiting rule for nonessential purchases above a certain dollar amount. This simple strategy allows you to reflect on whether the item is truly necessary.
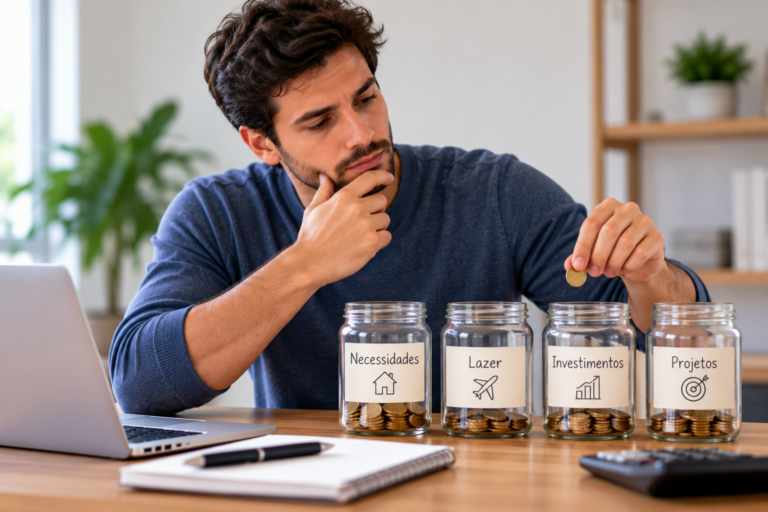
Another effective method is to set up separate checking accounts or use prepaid spending cards for discretionary purchases. This way, you can easily track your spending without dipping into essential funds.
Consider lowering your credit card limits and setting up transaction alerts. This approach can help you stay informed about your spending and reduce the likelihood of overspending. Manual approval for larger purchases can also serve as a helpful barrier.
Identifying predictable triggers is essential. Late-night shopping, social media ads, and limited-time promotions can all lead to impulsive buying. Recognizing these triggers allows you to prepare and avoid falling into the trap of spontaneous spending.
Ultimately, a useful barrier should interrupt impulse behavior without causing missed payments or unnecessary stress. By thoughtfully integrating these strategies into your routine, you can take control of your spending and make more informed financial decisions.
Behavioral Finance Insights: How Frictions Influence Spending Habits
Understanding how psychological factors affect spending can change your financial habits. Impulse buying often stems from emotional states, urgency, and convenience. Recognizing these triggers is essential for managing spending effectively.
For instance, marketing strategies often use urgency and scarcity messaging to encourage quick purchases. When consumers feel that an item is in limited supply, they may act without fully considering their needs. This can lead to regrettable purchases that disrupt financial plans.
A brief pause before completing a purchase can create an opportunity to compare it with your budget or savings goals. This moment of reflection allows you to assess whether the item aligns with your financial priorities.
Here are some strategies to design effective spending constraints:
- Establish specific rules for nonessential purchases that are automatic yet flexible for genuine exceptions.
- Apply stronger barriers where the risk of regret is highest, rather than uniformly across all transactions.
- Review your results over time to adjust barriers if they feel ineffective or overly restrictive.
By implementing these strategies, you can increase the mental and practical effort required to complete discretionary purchases. This approach helps to preserve access to necessities while creating resistance around emotionally driven buying decisions.
| Behavioral Insight | Description |
|---|---|
| Urgency | Creates pressure to buy quickly, often leading to impulse purchases. |
| Rewards | Incentives can motivate spending, especially when tied to emotional states. |
| Scarcity Messaging | Limited availability can trigger fear of missing out, prompting hasty decisions. |
| Convenience | Easy access to purchasing options can lower the barriers to impulse buying. |
Practical Ways to Add Financial Friction in Everyday Life
Adding small obstacles to your buying process can encourage more thoughtful spending. Implementing practical friction can be done without sacrificing financial flexibility. Here are some effective strategies:
Payment Delays and Cooling-Off Periods
One effective way to create financial friction is by introducing payment delays. For instance, you can impose a personal cooling-off period. This could mean waiting 24 to 48 hours before making nonessential purchases. This pause allows you to reassess whether the item is truly necessary.
Additionally, consider deleting stored card details from your favorite shopping sites. This simple step makes checkout less automatic and encourages you to think before you buy. Turning off one-click purchasing can also help by requiring more effort to complete a transaction.
Using Technology and Apps to Reinforce Friction
Technology can be a powerful ally in managing your spending. Enabling alerts for transactions above a selected amount can keep you informed about your spending habits. This way, you remain aware of your financial activities and can adjust accordingly.
Another effective strategy is to set up automatic transfers to savings or investment accounts. By directing money away from your checking account, you reduce the funds available for spontaneous spending. This method reinforces a habit of saving while still allowing access to necessary funds.
Creating a written list of exceptions for essential purchases—like groceries, medication, and transportation—can also be beneficial. This list helps you differentiate between needs and wants, making it easier to avoid impulse buys.
Finally, establish a simple review process: identify the purchase, record the trigger, wait, reassess, and then decide. This structured approach helps you make more informed financial choices.
Financial Frictions in Digital and Online Marketplaces
The rise of digital marketplaces has changed how we think about spending and impulse purchases. Online shopping has made buying faster and more convenient, but it can also lead to hasty decisions. Instant payments and reduced barriers create a unique challenge for consumers trying to manage their spending.
Online design often makes purchasing fast, repetitive, and emotionally persuasive. Features like stored payment credentials and one-click checkout streamline the buying process. However, this convenience can shorten the time available for reflection, increasing the likelihood of impulse purchases.
Challenges of Instant Payments and Reduced Barriers
Digital platforms reduce transaction costs, which can be beneficial. Yet, the ease of access may also encourage immediate demand without adequate consideration. Personalized recommendations and countdown offers can transform casual browsing into urgent buying decisions.
To counteract these tendencies, consumers can introduce friction into their shopping experience. For example, disabling stored payment details can create a practical pause. This simple step encourages you to think twice before completing a purchase.
Strategies to Introduce Friction in E-Commerce
Here are some effective strategies to help manage impulse buying in online marketplaces:
- Consider adding items to a wishlist first. This allows you to review your selections later rather than purchasing immediately.
- Separate browsing from checkout. Take time to reflect on whether the items are truly necessary.
- Apply a mandatory waiting period for nonessential orders. This can help you reassess your needs before finalizing a purchase.
- Use purchase approvals for larger transactions. This adds a layer of consideration before spending.
- Be mindful of how easy digital payments can lead to impulsive buying. Balance convenience with deliberate decision-making.
Ultimately, understanding the role of friction in online shopping can empower consumers. By implementing these strategies, you can navigate the digital marketplace more thoughtfully and reduce the chances of impulsive purchases.
| Strategy | Description |
|---|---|
| Disable Stored Payment Details | Creates a pause in the purchasing process, encouraging reflection. |
| Add to Wishlist | Allows for later review, reducing immediate demand. |
| Mandatory Waiting Period | Encourages reassessment of nonessential purchases. |
| Purchase Approvals | Adds a layer of consideration for larger transactions. |
The Broader Economic Role of Financial Frictions
The role of barriers in economic systems can significantly shape market efficiency. Understanding how these obstacles operate helps illuminate their dual nature in promoting stability while managing risks.
Some market frictions can actually improve efficiency. For example, they help screen borrowers, verify information, and discourage reckless risk-taking. By creating a careful selection process, these barriers can enhance the overall quality of lending and investment.
However, complete liquidity isn’t always desirable. If liquidity is too high, it can encourage excessive leverage or fragile financing structures. This creates a trade-off between fast access to funds and protection against sudden withdrawals or speculative behavior.
Liquidity spirals often occur when falling asset values reduce borrowing capacity. This situation forces additional selling, further exacerbating market instability. Therefore, understanding these dynamics is crucial for policymakers and consumers alike.
The right amount of friction depends on the goal, the risk involved, and the people affected. Balancing efficiency and stability requires careful consideration of the economic context and the potential consequences of these barriers.
| Type of Friction | Effects |
|---|---|
| Borrower Screening | Improves lending quality and reduces risk. |
| Excessive Liquidity | Encourages leverage and fragile financing. |
| Liquidity Spirals | Can lead to forced selling and instability. |
| Economic Goals | Balance between efficiency and risk management. |
Myths and Misconceptions about Financial Friction
Many people hold misconceptions about the role of barriers in managing their spending. It’s important to clarify that not all obstacles are detrimental. In fact, some measures can promote stability and encourage due diligence.
Adding friction to discretionary spending does not mean restricting access to essential funds. Instead, it allows for a thoughtful pause, helping individuals assess their true needs.
Moreover, financial friction is broader than just fees. It encompasses delays, uncertainty, collateral requirements, information gaps, and the effort involved in making purchases.
It’s essential to distinguish between personal spending rules and external constraints imposed by banks or financial crises. A personal rule can empower you, while external constraints may limit your choices.
Finally, the misconception that one tool fits all needs to be addressed. Each person’s financial habits and goals are unique, and friction should be tailored to match those differences.
| Myth | Clarification |
|---|---|
| All financial friction is harmful | Some barriers support due diligence and stability. |
| Friction restricts essential spending | Adding friction applies only to discretionary purchases. |
| Financial friction is just about fees | It includes delays, uncertainty, and information gaps. |
| Personal rules are the same as external constraints | Personal rules empower; external constraints limit. |
| One tool works for everyone | Friction should match individual habits and goals. |
Future Directions: Innovations and Research in Financial Frictions
The landscape of consumer finance is evolving rapidly, presenting new challenges and opportunities. As we move forward, researchers and policymakers are focusing on how to better understand the complexities of spending and borrowing.
Emerging models in macroeconomics aim to represent nonlinear crises and the diverse nature of firms. These models consider how changing financial institutions can affect economic stability. Policymakers are particularly interested in new forms of digital credit, instant payments, and stablecoins. These innovations may reshape the way consumers access funds and make purchases.
Emerging Models and Policy Debates
Current research continues to examine banking vulnerabilities and credit constraints. Understanding these factors is crucial as they impact the broader economy. For instance, jobless recoveries and uncertainty shocks highlight the need for adaptable financial systems.
Discussions around nonbank financial intermediation are also gaining traction. This shift could lead to new methods of managing liquidity and consumer protection. As these models evolve, they may provide insights into the resilience of financial systems.
Impact of New Financial Technologies
Technology can offer adaptive friction that changes according to risk, spending patterns, or user preferences. This adaptability may help consumers make more informed decisions. However, it also raises questions about consumer protections when automated systems make credit or purchasing decisions.
Future research will likely connect household behavior with digital-market design. This connection is vital for enhancing financial-system resilience. By understanding how consumers interact with technology, we can create a more stable economic environment.
Conclusion
Understanding the barriers to spending can lead to better financial choices. These obstacles impact how quickly and easily money flows through households, businesses, and markets. While macroeconomic barriers can worsen crises, personal barriers can effectively reduce impulse purchases.
Practical tools for managing spending include cooling-off periods, spending alerts, and removing stored payment details. Setting up separate accounts for discretionary spending and automating savings can also help. Remember, it’s important to maintain easy access for necessities and emergencies.
The goal isn’t to complicate every financial decision. Instead, creating space for thoughtful choices can help you resist the urge to act on impulse when emotions run high.